Finance
February 24, 2026

Missed our Webinar? Here Is a Summary of Our FCH x IamExpat Webinar

During this session, we explained the full home-buying process in the Netherlands — from finding a property to receiving the keys.
Missed our Webinar? Here Is a Summary of Our FCH x IamExpat Webinar

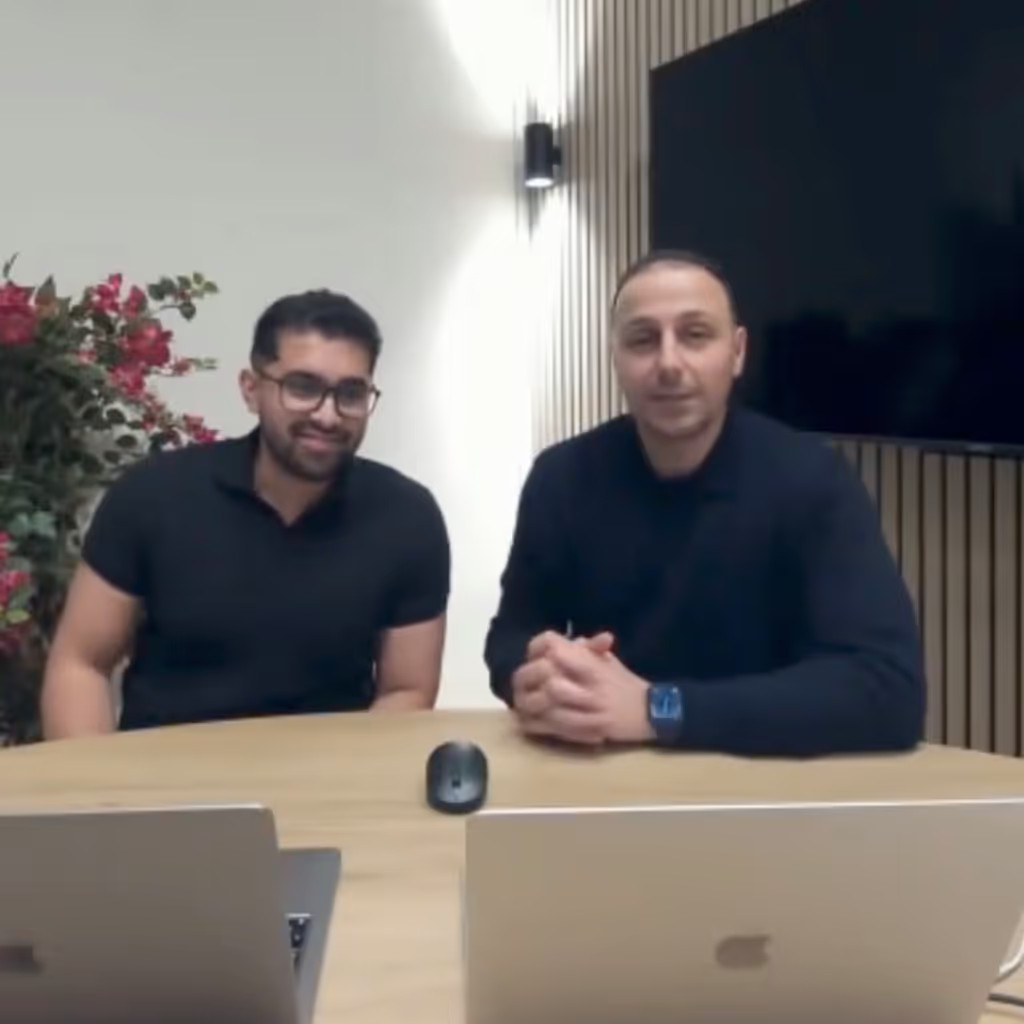
On 24th of Feburary, Financial Consultancy Holland (FCH) hosted a live webinar in collaboration with IamExpat, together with Danish from M&D Real Estate and Milad from Financial Consultancy Holland.

During this session, we explained the full home-buying process in the Netherlands — from finding a property to receiving the keys — especially tailored to expats and first-time buyers.

If you couldn’t attend, here is a clear and practical summary of everything we discussed.

‍

1. Can You Get a Mortgage in the Netherlands?

One of the biggest misconceptions is:

“I need a permanent (indefinite) contract to buy a house.”

That is not true.

✅ Temporary Contract

You can apply for a mortgage if:

  • You have a temporary contract with a letter of intent from your employer
  • You’ve been working in the Netherlands for at least one year

✅ Self-Employed / Business Owners

  • Normally banks ask for 3 years of income history
  • In some cases, it is possible after 1–2 years, but borrowing capacity may be lower

✅ Residence Permit

  • With a permanent or regular residence permit: 100% financing is possible
  • With certain temporary permits (e.g. intra-company transfer): financing may be limited to 90%

‍

2. How Much Can You Borrow?

In the Netherlands, you can finance:

💰 Up to 100% of the market value of the property

Important:

  • The bank uses the appraised market value, not just the purchase price.
  • If the appraisal is lower than your purchase price, you must cover the difference yourself.
  • If the appraisal is higher (rare in competitive markets), it can help reduce your own cash input.

Income Components That Count

We can include:

  • Base salary
  • Holiday allowance
  • Fixed 13th month
  • Structural bonuses (depending on the bank)

As independent mortgage advisors, we compare multiple lenders — unlike banks that can only offer their own products.

‍

3. What Are the Costs of Buying a €400,000 Property?

Here’s an example breakdown:

Cost Item Approximate Amount
Purchase price: €400,000
Transfer tax (2%): €8,000
Notary (transfer + mortgage deed): €2,000
Valuation report €925
NHG fee (if applicable): 0.4% of mortgage amount
Mortgage advisory fee (FCH): €3,495 (starter)

Good to Know

If you are:

  • Under 35 years old
  • Buying your first home
  • Purchase price ≤ €510,000 (2024 limit)

You may qualify for 0% transfer tax (instead of 2%).

‍

4. What Is NHG (National Mortgage Guarantee)?

Nationale Hypotheek Garantie (NHG) is a government-backed mortgage guarantee.

2024 NHG Limit:

  • €435,000
  • €461,100 if energy-saving measures are included

NHG Costs:

  • 0.4% one-time fee of the mortgage amount

Benefits:

  • Lower interest rate (typically 0.2%–0.4% lower)
  • Safety net in case of forced sale due to circumstances like divorce or unemployment

‍

5. Current Mortgage Interest Rates (Indicative)

At the time of the webinar, average 10-year fixed mortgage rates were approximately:

  • With NHG: around 3.5%–3.8%
  • Without NHG: around 3.8%–4.2%

(Exact rates depend on the lender, income, energy label, and market conditions.)

‍

6. Mortgage Repayment Options

There are three main types:

1️⃣ Annuity Mortgage

  • Fixed monthly payment
  • Interest portion decreases over time
  • Most common option

2️⃣ Linear Mortgage

  • Higher payments at the beginning
  • Payments gradually decrease
  • Faster equity buildup

3️⃣ Interest-Only Mortgage

  • Only pay interest
  • No automatic repayment
  • Rarely advised for primary residence

‍

7. Can You Finance Renovations?

Yes.

If you:

  • Buy for €400,000
  • Plan €50,000 renovation

The bank looks at the expected market value after renovation.

Important:
Renovation costs usually do not increase property value 100%. Often around 60–80% is added to market value.

The renovation budget is placed in a construction depot (bouwdepot) and paid out against invoices.

You can also borrow extra for:

  • Insulation
  • Solar panels
  • Energy-efficient upgrades

‍

8. The Buying Process – Step by Step

  1. Budget orientation (mortgage check)
  2. House hunting
  3. Viewing & bidding
  4. Offer accepted
  5. Mortgage application (4–6 weeks)
  6. Appraisal
  7. Bank approval
  8. Final inspection
  9. Notary appointment
  10. Receive the keys

‍

9. What Happens If One Partner Passes Away?

Without protection:

  • The surviving partner must qualify alone for the mortgage
  • If income is insufficient → property may need to be sold

With life insurance:

  • Insurance can repay part of the mortgage
  • The surviving partner can stay in the house

We strongly advise discussing this if you buy with a partner.

‍

10. Can You Rent Out Your Property?

If you buy a home to live in yourself:

  • Renting out is generally not allowed
  • Some banks allow temporary permission under strict conditions
  • Always check before assuming rental income is possible

‍

11. Can You Repay Early?

Yes.

Most mortgages allow:

  • Up to 10% extra repayment per year without penalty
  • Full repayment without penalty when selling the house

‍

12. Questions From Attendees (FAQ)

How long does the process take?

  • Finding a house: 1 week to several months
  • Mortgage approval: usually 4–6 weeks

Can I buy without physically viewing the house?

We strongly advise viewing in person or via live video call. Buying without inspection is risky.

When do I pay FCH’s fee?

Only after the bank gives final mortgage approval.

What does FCH charge?

  • Starters: €3,495
  • Self-employed: €4,000
    No cure, no pay.

What if I want to sell and buy at the same time?

Possible, but requires careful coordination. We guide clients through this structure.

Can I use equity from my current home?

Yes — if your income supports the higher mortgage.

Why This Webinar Matters

Buying property in the Netherlands is possible — even as an expat, freelancer, or first-time buyer — but clarity is key.

At Financial Consultancy Holland, our mission is to provide:

  • Transparent advice
  • Clear communication
  • Independent comparison of lenders
  • Guidance from start to key handover

As mentioned in our official company overview

FCH Prompt

, we focus on helping expats and first-time buyers navigate the Dutch mortgage system with confidence.

‍

Missed the Webinar but Want Personal Advice?

Every situation is different.

If you want:

  • A personalized borrowing calculation
  • Advice about your contract type
  • Guidance on NHG eligibility
  • Support with renovation financing

Contact us directly:

📍 Boompjes 40, 3011 XB Rotterdam
📞 0622870981
📧 info@fc-holland.nl

Or book an appointment through our website and mention “Webinar” in the comments.

We’re here to make your home-buying journey clear, structured, and successful.

Would like to know about your possibilities in the Netherlands? Fill in the form below and let's get in touch.